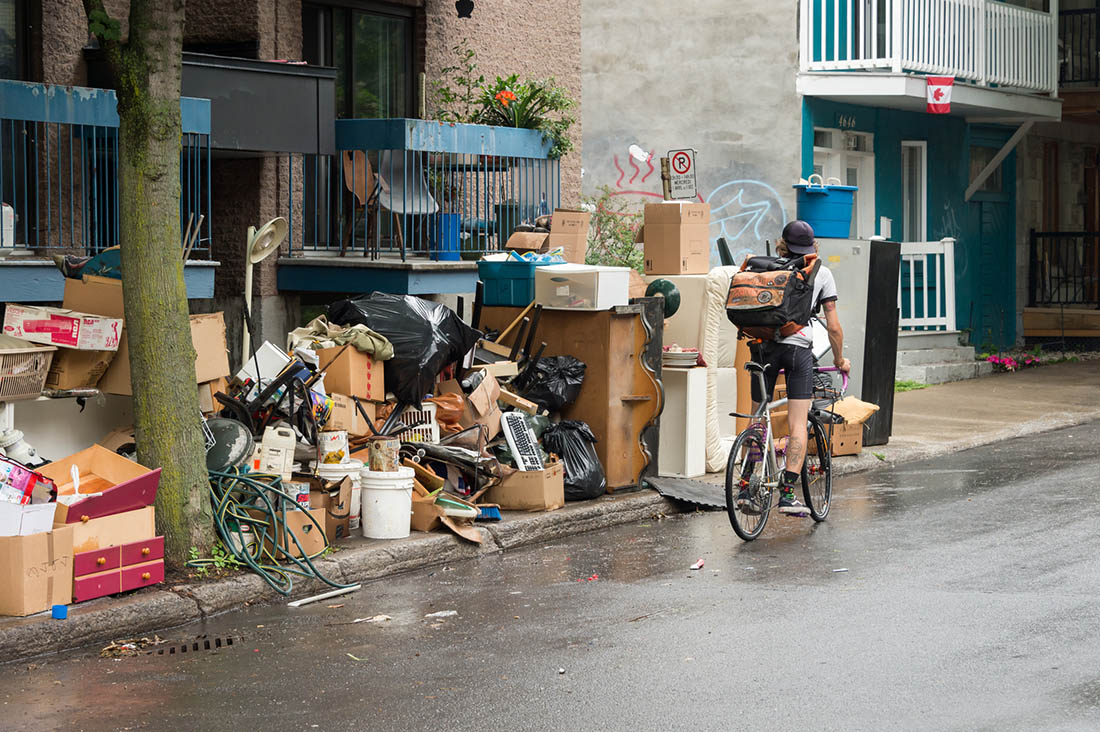
Catégorie

Education

What does it take to be investment-ready?

Par Education

⏱️ 4 min read  

Investment readiness means having the clarity, financial foundation, internal capacity, and community understanding to make informed decisions about raising capital. For organizations considering community bonds, that means having a clear project, a strong financial case, a sense of who might invest, and a team prepared to take on the responsibilities that come with investment. 

What does that actually look like in practice? And how can an organization move from “we have a big project and need funding” to “we’re ready to explore investment”? 

That’s the gap Tapestry’s Community Capital Readiness Program is designed to help organizations bridge. Applications for Tapestry’s Fall 2026 Community Capital Readiness Program are open until September 14, 2026. The program begins on October 2 and is open to Canadian charities, nonprofits, and co-operatives developing or preserving community-owned land or infrastructure.

Learn more and apply

Start with a clear project 

Before people can invest in your project, they need to understand it.

How much capital do you need? What will it fund? What will the project make possible? Where does a community bond fit into your overall financing plan?

Organizations often come to the Readiness Program with a compelling project but need to sharpen the details. The Readiness Program helps participating organizations work through these questions and turn them into a clear project brief. 

It’s an opportunity to get everyone on the same page about the project, the financing need, and the impact you will have. That clarity will also make it easier to communicate the opportunity to your board, partners, and potential investors later.

Know what the numbers say
Nick Yeo, Director of Client Services

A project can be important to a community and still not be financially ready for investment.

Investment readiness requires a realistic understanding of costs, revenue, ongoing expenses, cash flow, and the organization’s ability to take on additional financial obligations. It also means understanding how new investment would interact with existing financing, such as mortgages or other debt. 

The Readiness Program’s financial modelling process allows you to test different scenarios before committing to a raise. What happens if revenue is lower than expected? What if costs increase? Can the organization meet its existing obligations while also repaying investors? Could changing the project timeline or financing structure improve the picture?

As Tapestry’s Director of Client Services, Nick Yeo, explains: “The financial model gives organizations levers to pull. You can test different timelines, revenue assumptions, costs, or financing structures and see what happens. Sometimes the answer is that a community bond could work really well. Other times, you realize you need to change the plan, or that now isn’t the right time. Either way, you come away with information that helps you make a better decision.” 

That’s an important part of investment readiness and the Readiness Program: the goal isn’t necessarily to decide that you should raise investment. It’s to have enough information to decide whether, when, and how.

Build organizational capacity

Investment readiness also depends on your organization itself. Does your organization have reliable revenue to support repayment? Is your team comfortable managing debt and cash flow? Does your board understand the risks involved? Does your organization have the fundraising, financial, and governance capacity to take on a new financing relationship?

“Investment readiness is about having the financial position, organizational capacity, governance, and skills to take on investment and manage the obligations that come with it,” says Nick. 

For organizations that aren’t there yet, that doesn’t mean investment is off the table. It may mean there are areas to strengthen first — from financial systems and internal expertise to governance, cash-flow management, or experience with other forms of financing. The Readiness Program helps organizations identify those gaps and understand what it would take to address them.
Understand who could invest

Having a large community of supporters is a great starting point, but investment readiness requires going a step further.

Who are the people and organizations connected to your work? What motivates them? How much might they realistically invest and under what terms? Are they experienced investors, or could this be their first investment in a community project? What questions or concerns might they have?

The Readiness Program helps organizations map their potential investor community and build detailed investor profiles. That means looking beyond existing donors or beneficiaries and considering the wider community around a project. That might include local businesses, community groups, foundations, and people connected through tangential, shared interests. This deeper understanding of your investor audience becomes the foundation for a future investor engagement and communications strategy.

From “not ready yet” to investment-ready

Tapestry’s Readiness Program brings all these pieces together. Over two months, participating organizations work through Tapestry’s tools and templates, learn from successful community bond issuers, and receive a combination of group learning and individualized support. 

By the end of the program, an organization may be ready to move toward a community bond raise. It may decide to strengthen its financial or organizational capacity first. Or it may determine that another financing option is a better fit. All three are valuable outcomes.

The work you’re doing in the Readiness Program applies beyond community bonds. A stronger financial model, clearer project story, better understanding of interested parties, and greater confidence communicating about the project can strengthen conversations with banks, funders, donors, partners, and other sources of capital.

Investment readiness is really about being prepared to make a good financing decision and having the tools and understanding to act on it. 
Could these five policy changes unlock more community capital?

Par Education, Policy and Advocacy

⏱️ 4 min read  


You have a project to build and you need capital to make it happen. As a community-focused organization, you’re also thinking about where the capital comes from and who gets to benefit from that investment. 

What if more Canadians could invest directly in projects like yours? 

The Canadian Coalition for Community Capital (4C) is working to change that. Co-founded by Tapestry Community Capital, the Coalition is a national advocacy network of more than 30 organizations working to strengthen the policy environment for community investment. 

In its May 2026 pre-budget submission, the Coalition proposed five targeted federal reforms that would make community investment easier, safer, and more attractive to everyday Canadians — ultimately expanding the pool of investors interested in impact organizations like yours.

Here’s what each proposal could mean for organizations issuing community bonds.

1. A bigger pool of potential investors

Today, Canadians can technically hold a community bond or preferred co-op share in a registered account, but generally only if it is asset- or mortgage-backed. That’s a requirement many community organizations can’t meet, or can only meet at a prohibitive cost. 

The Coalition is asking the government to allow unsecured community investments of up to $20,000 per year to qualify for registered accounts. That would let everyday investors benefit from the same tax sheltering available for other eligible investments. The annual limit would also help preserve the role of registered accounts as savings and retirement tools. 

For you as an issuer, that could mean access to a much larger pool of investors including people who already have money set aside in RRSPs, TFSAs, or FHSAs, and would prefer to put some of it work in their community. 

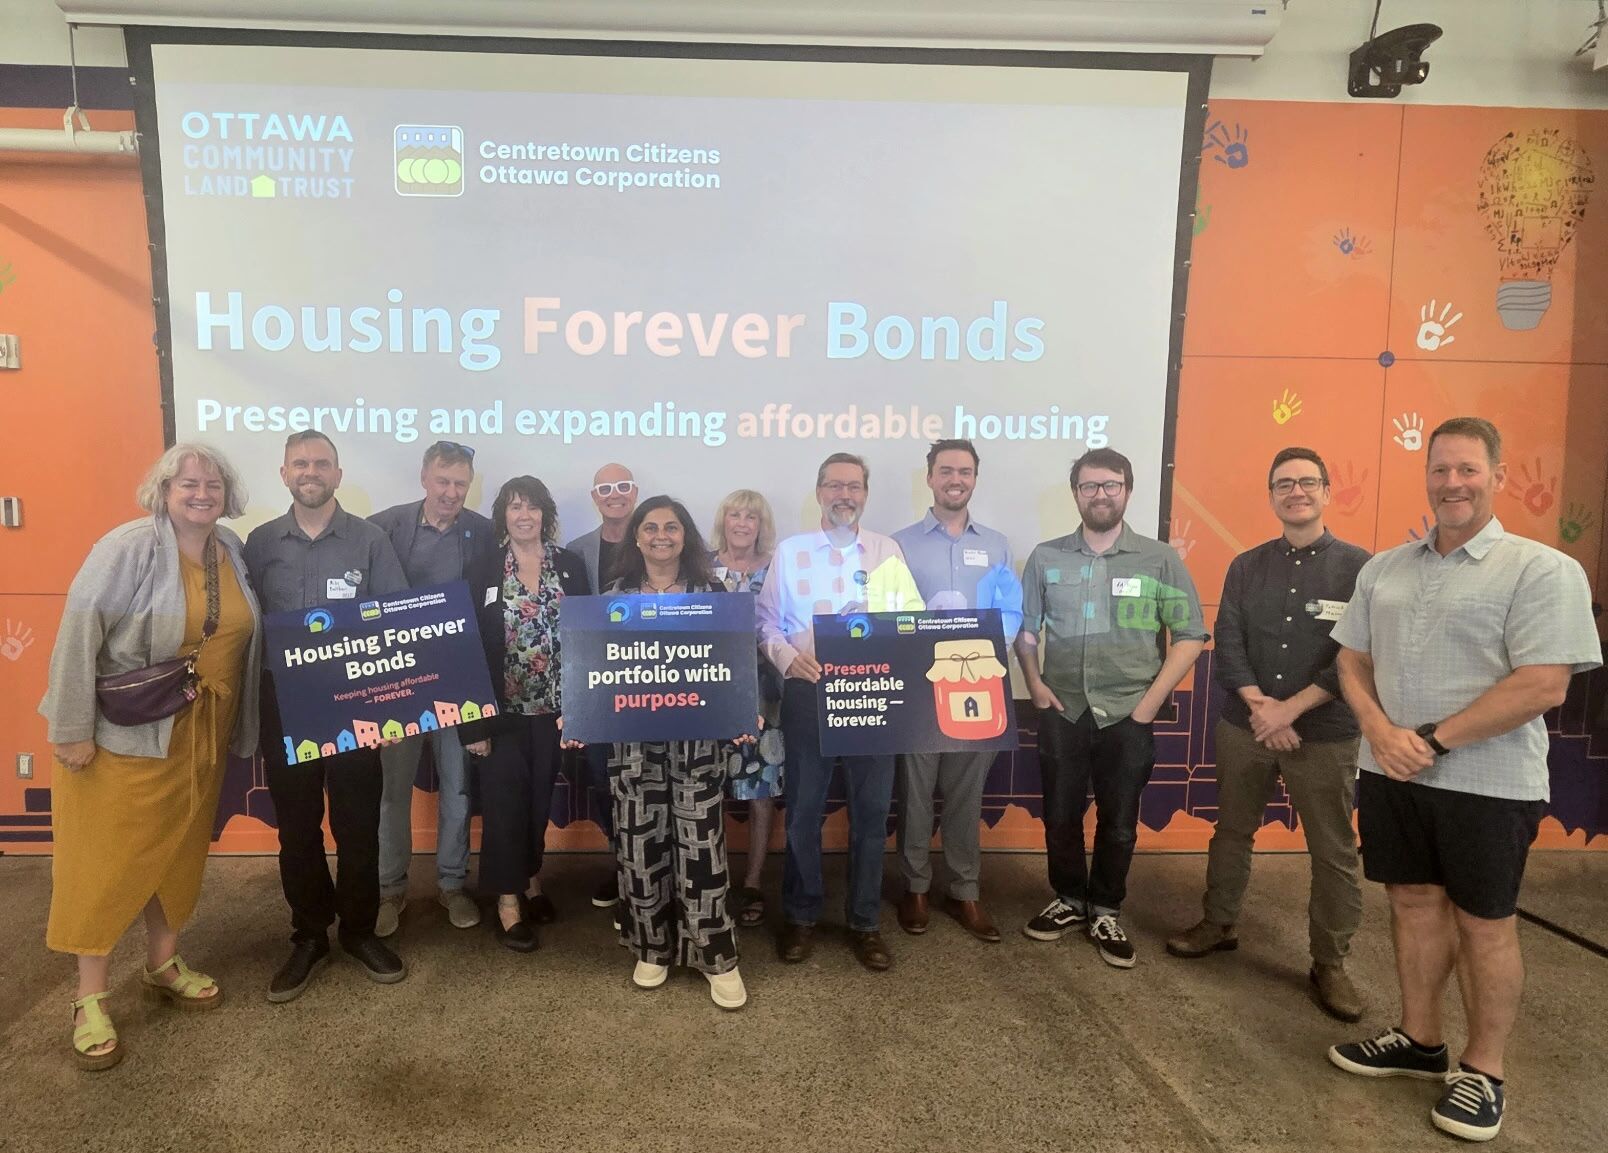
It also responds to something issuers are hearing directly from their bondholders. At the Ottawa Community Land Trust (OCLT), more than 200 investors have invested over $4.5 million in Housing Forever Bonds since 2024. 

“We know that people are keen to invest their capital right here in the community to advance housing security for their neighbours,” OCLT Executive Director, Mike Bulthuis, says. “While this response is incredible, we know that other investors would come forward if investing in community was easier, or if they could add Housing Forever bonds to their RRSPs, TFSAs or First Home Savings Accounts.”

2. More protection if things go wrong

As with any investment, there are risks associated with investing in community bonds. For potential investors, uncertainty about losing their money can be a barrier to investing in the first place.

Tapestry’s Community Bondholder Survey found that approximately 25% of respondents identified concerns about risk or security when investing in community bonds. 

The Coalition is proposing that investors be able to deduct 75% of losses on eligible community investments from their taxable income. If an investor loses money on an eligible community investment, they would be able to recover some of that loss through the tax system. The idea is to recognize the public benefit of these investments while reducing some of the financial risk for everyday investors.

For issuers, this could make it easier to have conversations with prospective investors who like your project but are concerned about what happens if the investment doesn’t work out. A policy that gives investors some protection could increase their confidence in community investment and make more people willing to consider your offering.

3. A stronger financial incentive to invest 

People invest in community projects because they want their money to do good, but they also need the investment to make financial sense. 

The Coalition is proposing a 30% Community Capital Tax Credit, made up of a 20% non-refundable credit and a 10% refundable credit. For investors, that would make the financial case for investing in community projects much stronger — especially for lower- and middle-income Canadians. 

Over time, that could help organizations like yours build larger and more diverse investor bases – and keep more of the financial benefits of your projects within the communities you serve.

4. More ways for co-operatives to raise capital

If you’re a co-operative, your ability to raise capital can be limited by who is eligible to invest – mainly, your existing membership base. The fourth reform would allow co-operatives to raise investment capital beyond their membership. 

That would give you more flexibility when you need to finance a project and open the door to new investors who support your work but aren’t members. 

And even if you’re not a co-operative, this change could help grow the community investment market as a whole. The more organizations that raise community capital, the more people will encounter community investment, gain experience as investors, and become familiar with putting their money into local projects. A bigger and more familiar community investment market could make it easier for you to raise capital over time. 

5. More support for organizations raising capital

As an issuer, you need the expertise, infrastructure, and financing tools to develop an offering and bring it to market. The Coalition’s fifth reform addresses this side of the equation. It calls for national accreditation for community finance issuers, incubators, and intermediaries, alongside a $250 million federal fund for technical assistance, guarantees, first-loss capital, and low-interest financing. 

For organizations like yours, this could help address one of the less visible barriers to raising community capital: the infrastructure needed to actually build a successful offering.

What could these changes mean together? 

Together, these changes could make it easier for Canadians to invest in community projects and easier for organizations like yours to raise the capital those projects need. 

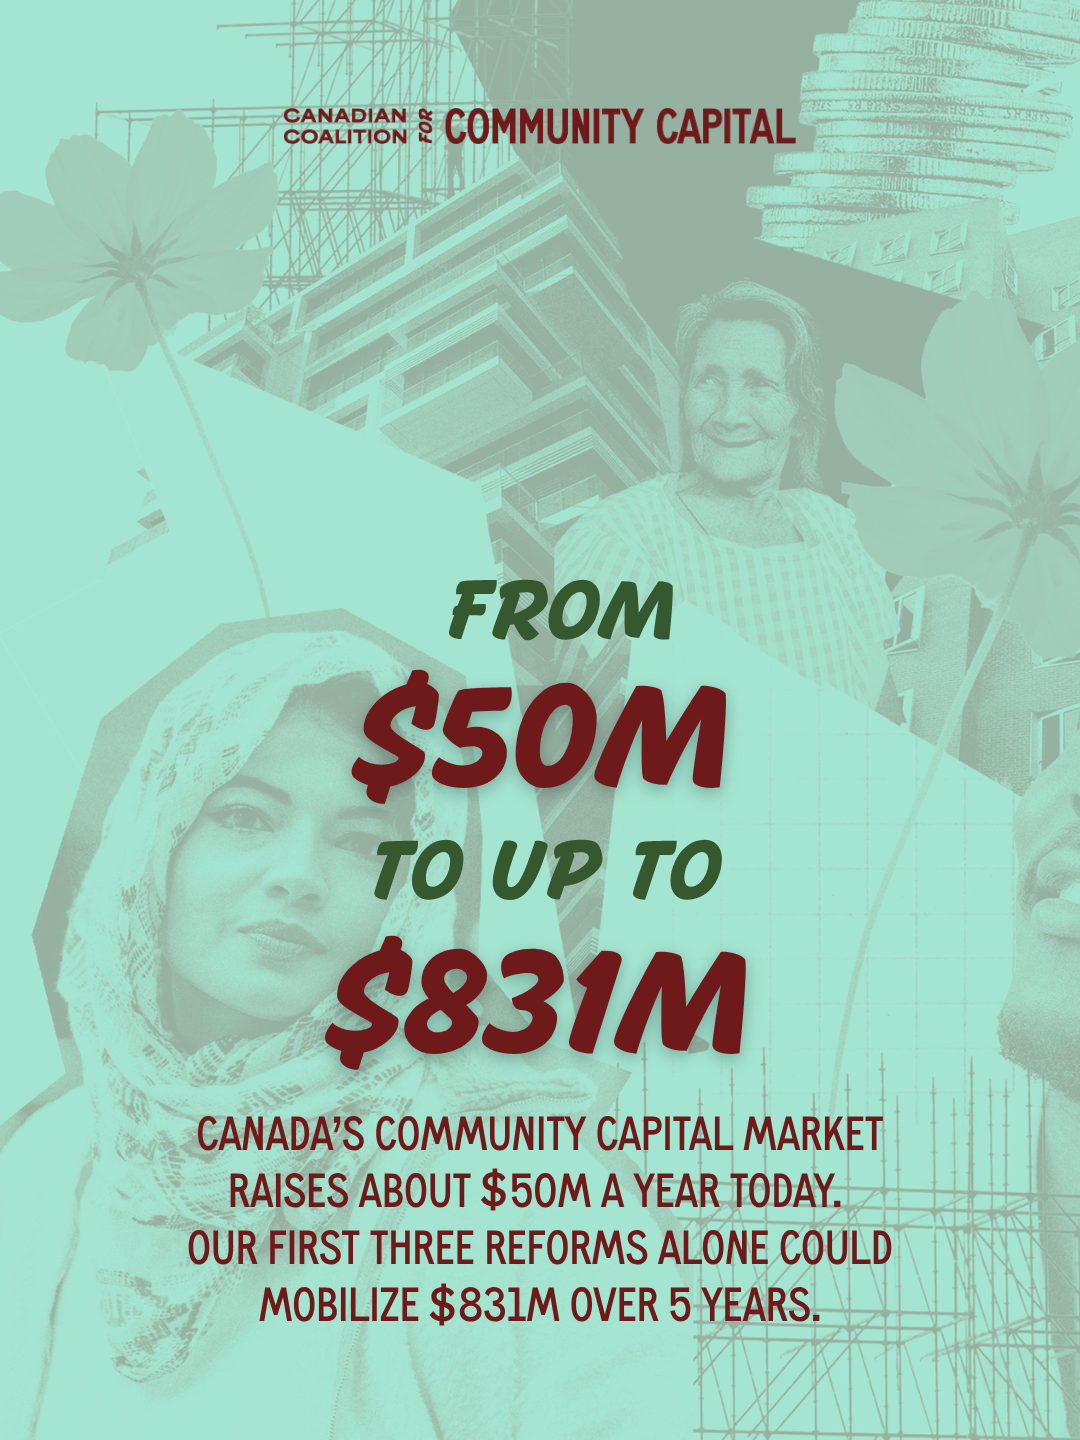
Independent economic modelling by Nordicity estimates that the reforms could mobilize up to $831 million in community capital over five years. 

A stronger policy environment means more people can participate in community investment – and more organizations have a chance to raise the capital they need to build the projects their communities need. 

Learn more about the Coalition’s five proposals here.

Community bonds vs. social impact bonds – what’s the difference?

Par Education

⏱️ 2 min read  
 

They sound similar, but they’re not! 

Community bond: you finance an asset

A non-profit, charity, or co-operative needs capital to purchase an asset, like real estate or major equipment. Instead of going to a bank, they come to their community. Investors (mostly everyday people, but also businesses and other organizations) lend them money, earn interest, and get repaid from the organization’s own revenue – rent, fees, sales, whatever revenue they generate using the asset. 

Similar to a traditional bond, it’s an interest-bearing loan with a set rate of return and a fixed term. The key difference: because the issuing organization is a non-profit, charity, or co-op, the investment generates a financial and a social return. 

The idea is that organizations can offer investment opportunities and returns to their communities, not just to big commercial lenders. They can also set the interest rate and maturities that work best for their project, instead of accepting the bank’s terms. 

Example: In 2024, the Ottawa Community Land Trust raised $3M from 132 investors – neighbours, small businesses, foundations – to buy and preserve affordable rental housing in Ottawa. 

Social impact bond: you finance an outcome 

A government agency identifies a social outcome it wants to achieve such as reducing youth incarceration rates or increasing post-secondary enrolment. A private funder (business, foundation, trust, accredited investor, etc.) agrees to finance the program required to get there. An external organization delivers the programming. If the outcome is achieved, government pays the funder a predetermined amount. If the outcome isn’t achieved, the funder gets nothing.

Despite the name, a social impact bond isn’t really a bond. It’s a pay-for-performance contract. In fact, they’re increasingly known as social outcomes contracts. The idea is that the government only pays for what works, which saves public money and incentivizes funders to back evidence-based programs with a real shot at success. 

Example: The world’s first social impact bond launched in the UK in 2010. Social Finance UK raised £5M from 17 private investors to fund rehabilitation support for short-sentenced prisoners at HMP Peterborough. The program reduced reoffending by 9%, exceeding the 7.5% target, and investors were repaid with a return of just over 3% per year. 

So… what’s the difference?

Community bond

Social impact bond 

Who can invest

Anyone (typically minimum $1,000) Typically businesses, foundations, trusts, institutional investors

Who repays you

The issuing organization (non-profit, charity, co-operative)  The government

Repayment is based on…

The organization’s revenue  Outcomes achieved

Best for 

Capital projects with real assets Large-scale social programs 

Community bonds are for organizations with a revenue model and a community willing to invest directly. Social impact bonds are for governments with a specific social outcome in mind and funders willing to bet on it. 

They’re different tools for solving different problems, both effective.

Interested in learning more about community bonds? Get in touch!

Climate solutions need community capital 🌍

Par Education

⏱️ 2 min read
 

Earth Day tends to bring a wave of optimism. 

Clean energy feels like it has momentum. Many people want to be part of the solution. Communities want projects that improve resilience, create local benefits, and make progress visible. 

When you look at how projects get built, everything starts with capital. Solar projects, building retrofits, EV charging networks, and other climate infrastructure all require upfront capital long before any benefits show up. That early stage is where projects either move forward or stall. And for the most part, that stage is still concentrated with a relatively small group of institutions and investors. 

Meanwhile, public interest keeps growing. A 2025 Mackenzie study found that 67% of Canadians believe energy transition investing has a positive impact, but only 14% are currently participating, and just 6% know how to get started. That gap points to a system that hasn’t made participation easy to step into. 

SolarShare: making climate investment tangible

SolarShare in Ontario is one example of what changes when pathways to participation exist. 

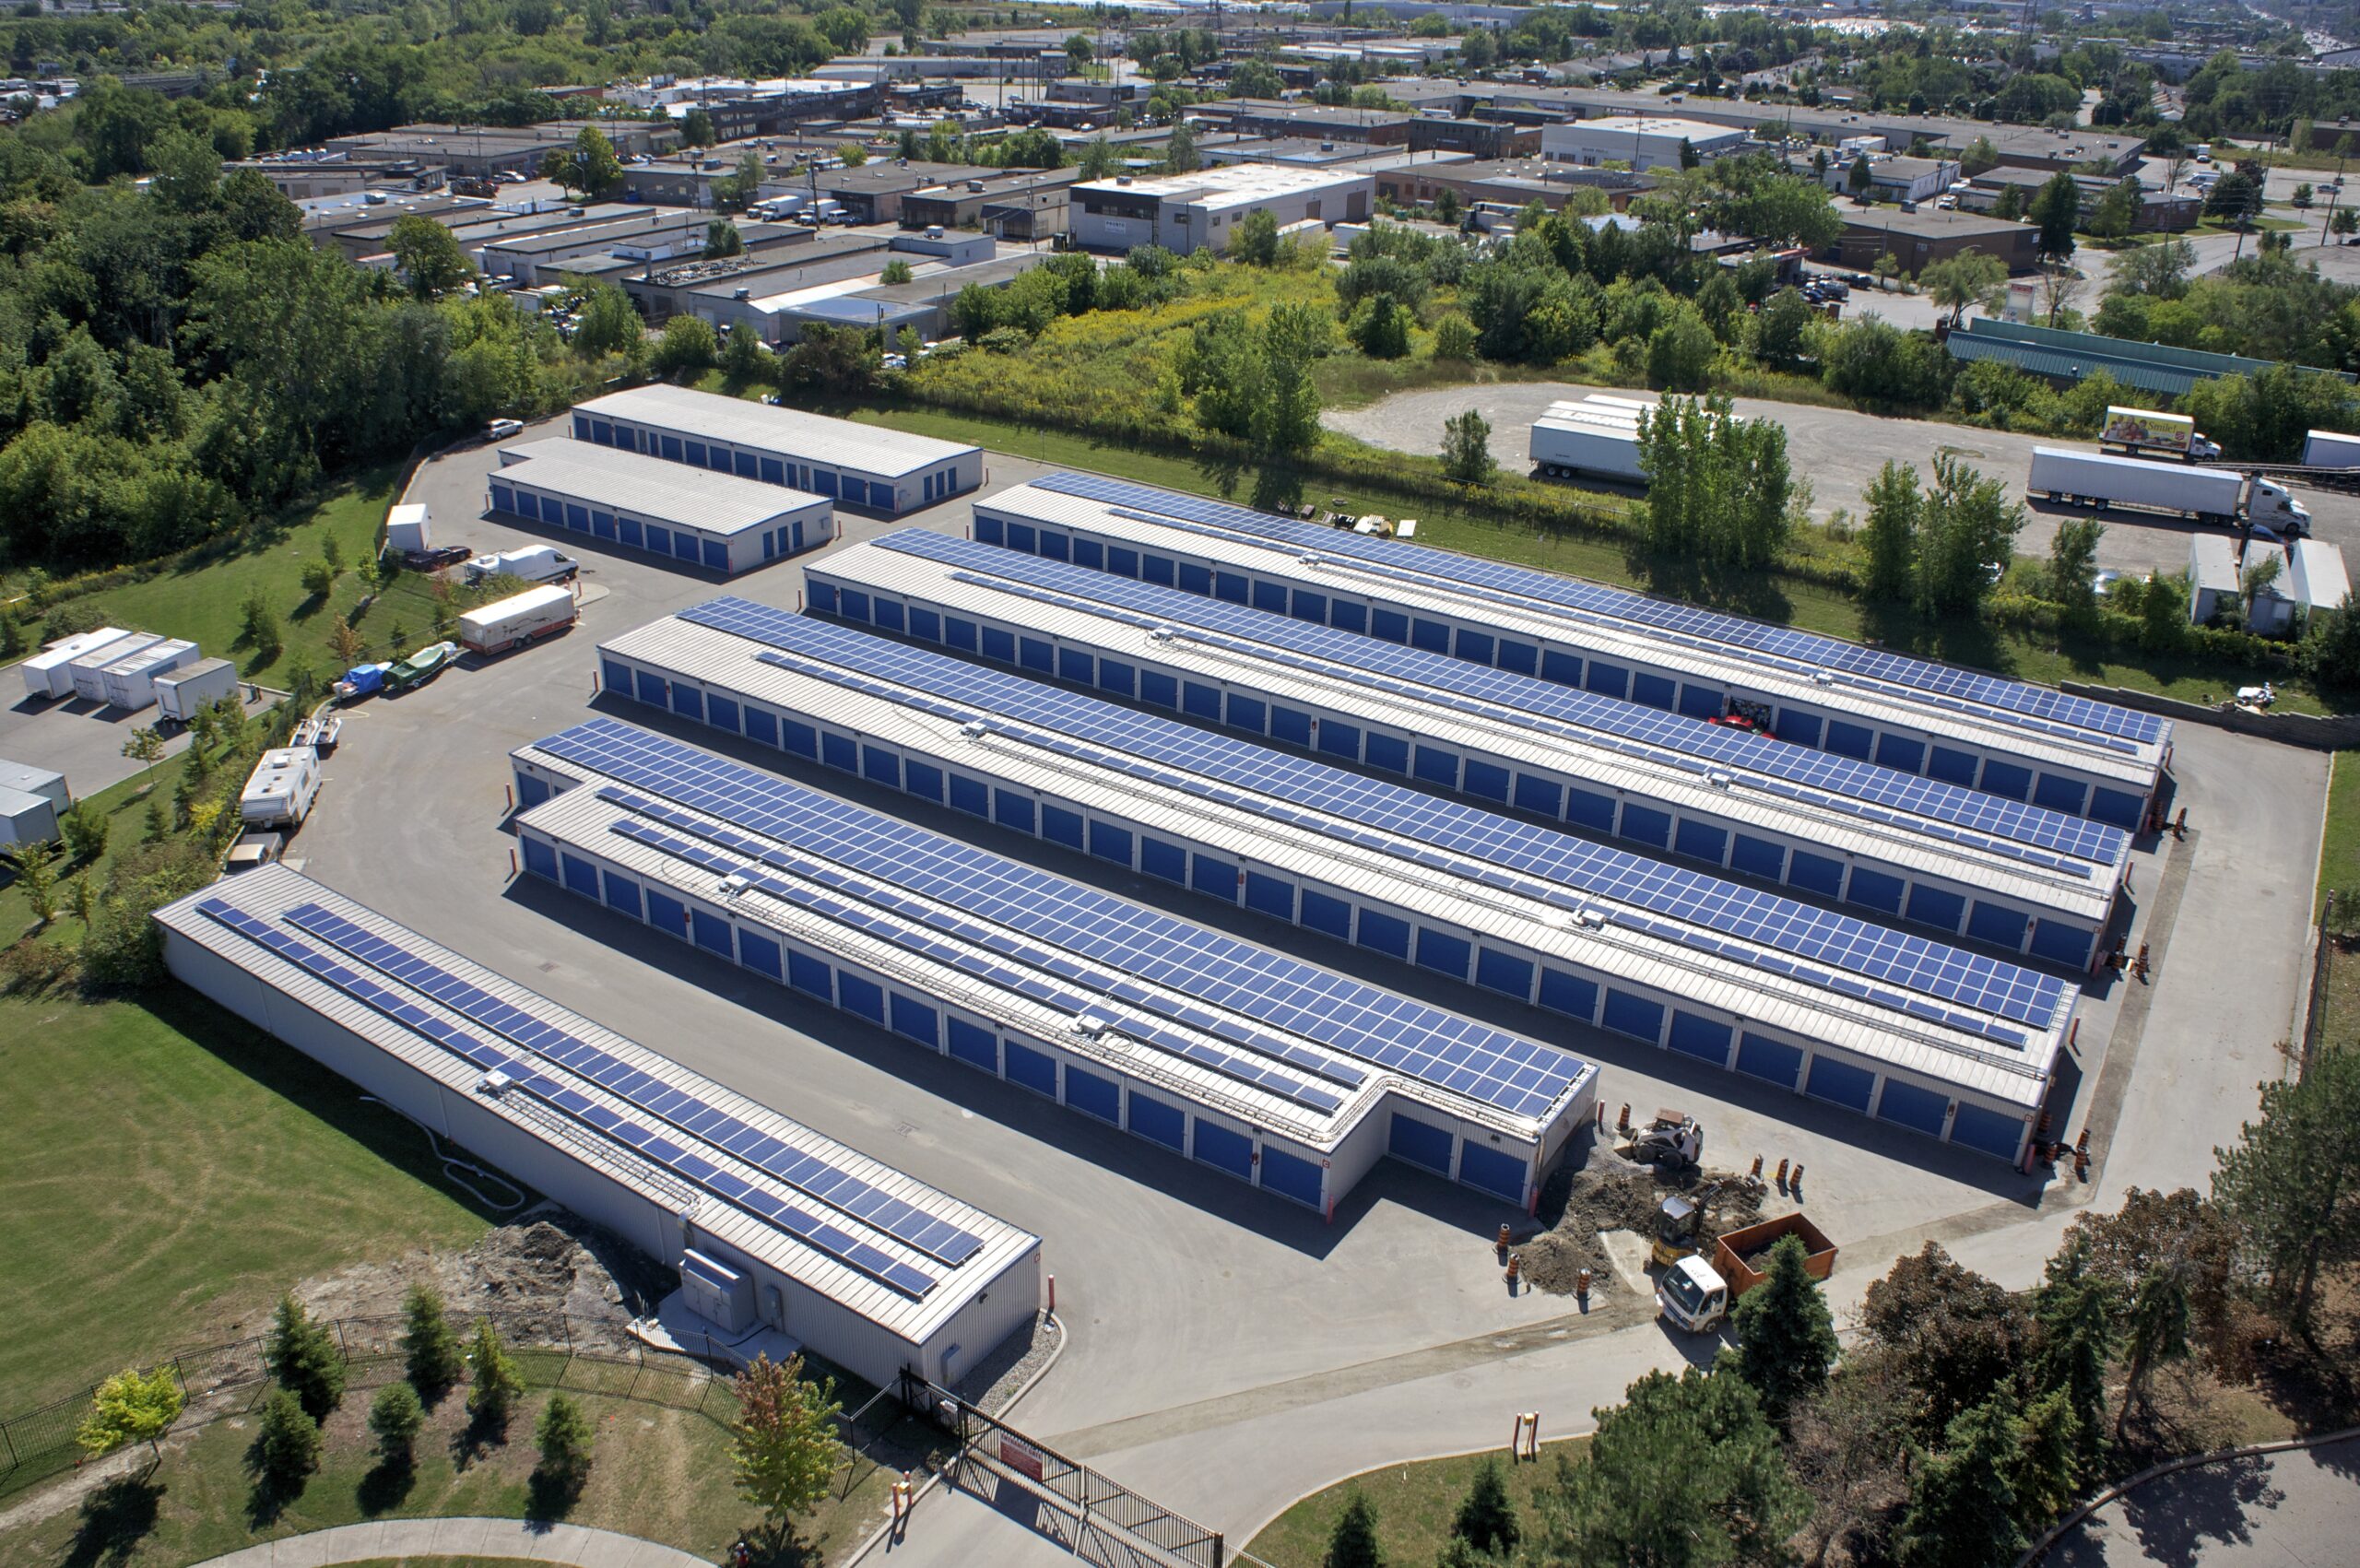
It was founded in 2010 as a renewable energy co-operative, incubated by the Toronto Renewable Energy Co-operative (TREC). SolarShare’s goal was to let people invest directly in solar energy projects through community bonds. 

What started with three projects has grown into more than 50 solar installations across the province and more than 2,000 people investing over $80 million. 

SolarShare demonstrates that everyday people are willing to put their money into renewable energy when the opportunity is clear, practical, and connected to something real.

What changes when participation is real 

Community capital works because it closes the distance between people and the things they’re helping build. 

Less distance between investment and impact. Less distance between intention and action. Less distance between “I support this” and “I’m part of this.” 

When that distance shrinks, projects feel less external and more shared. SolarShare is one example of that in practice. 

Community bonds are being used across sectors such as renewable energy, affordable housing, arts & culture, and more. Different sectors, same underlying shift: capital structured in a way that broadens participation and changes who gets to own and benefit from what is built.

Earth Day, from that perspective

Earth Day usually focuses on awareness and urgency. As it should. 

The 2026 theme, “Our Power, Our Planet”, adds something important to that: participation. Climate progress is shaped by the people involved in building it. That’s where community capital fits in. 

Tools like community bonds give people a way to move from supporting climate solutions in principle to helping finance them in practice through direct participation in real projects. 

This Earth Day, we’re celebrating the people who choose to invest in something bigger than themselves. The communities that decided to build their own future. And the financing models helping make it possible. 😊


Disclaimer: This content is for general informational purposes only. It does not constitute legal, financial, accounting, or tax advice, and should not be relied upon as such.

3 myths about investing in community bonds

Par Education

⏱️ 2 min read 
 

Community bonds are an increasingly popular way for people to invest in projects that create social, environmental, and cultural impact. 

Let’s look at three myths about investing in community bonds – and the reality behind them: 

Myth 1: Community bonds are only for wealthy investors 

Reality: Anyone can invest. 

Over 80% of investors in Tapestry-led community bond campaigns are retail investors. You don’t need to be a millionaire to invest in your community. Most campaigns are intentionally designed to be accessible, with investment minimums often starting at $1,000, giving more people the chance to support projects they care about. 

At their core, community bonds are about democratizing finance. That means making it possible for more people to invest in the resilience and future of their communities.

Myth 2: Community bonds are just donations

Reality: Community bonds are investments, not donations. 

While donations and community bonds can both support impactful projects, they serve different purposes. 

Donations are given without the expectation of getting your money back. Community bonds, on the other hand, are structured investments. You provide money to a nonprofit, charity, or co-op, and receive your principal back with interest. 

Community bonds are a way to align your money with your values. You’re making an investment that benefits both your pocket and the community! 

Myth 3: You have to live nearby to invest

Reality: You don’t have to be local to participate. 

Many community bond investors are closely connected to the organizations or projects they support, but you don’t have to live in the immediate community to participate. We see people across the country invest in projects they care about, even if they’re not directly affected. 

Community bonds connect people to missions and impact, not just locations. It’s about supporting projects you believe in, wherever you are. 


Community bonds are part of a broader shift toward a more inclusive and community-driven approach to finance. By clearing up some misconceptions, we hope more people feel confident exploring how they can support projects that matter to them.


Disclaimer: This content is for general informational purposes only. It does not constitute legal, financial, accounting, or tax advice, and should not be relied upon as such.

What nonprofit boards should be paying attention to this budget season 📊

Par Education

⏱️ 3 min read 


For many nonprofits across Canada, budget season is here. Boards are reviewing projections, approving operating plans, and making sure the year ahead looks financially sound. 

But budgets only tell part of the story

Across the sector, projects that seemed secure a year or two ago are hitting unexpected pauses:

  • A housing development waiting on a funding program that may not reopen.
  • A community centre renovation delayed as grants scale back. 
  • A capital campaign that’s 90% funded… still stuck waiting for that final piece of public funding to move forward. 

Alone, these challenges aren’t unusual. Taken together, though, they’re prompting boards to think more carefully about how projects are financed. This goes beyond whether the funding exists, but how it arrives, how it’s structured, and how different sources fit together. 

Timing matters

The reality is that capital projects rarely unfold in neat fiscal-year cycles. 

Funding might arrive in phases over several years, often tied to milestones or reporting requirements. Construction invoices, meanwhile, follow their own schedule. They probably don’t care about your budget calendar. Long gaps between committed funding and actual cash in the bank are common. 

Boards need to look at cash flow across the full life of a project, not just the annual budget. That way, boards can reveal pressure points early and sometimes even identify options to keep projects moving, rather than waiting indefinitely for the final piece of funding. 

A mix of funding sources is more important than ever

For a long time, certain public funding programs felt stable enough that organizations could confidently build projects around them. Now, not so much.

Public funding remains essential to nonprofit infrastructure in Canada, but timelines shift, priorities evolve, and programs sometimes pause between funding rounds. When a project depends heavily on one expected funding stream, a single change can stall years of planning. 

Increasingly, organizations are deliberately building a mix of complementary funding sources from the start: grants, public funding, philanthropy, and other forms of capital that provide flexibility when timing shifts. In finance circles, this is called blended finance. For boards, it simply means structuring projects so progress doesn’t depend on a single decision somewhere else in the system. 

The nonprofit financing toolkit is wider than many boards realize

Organizations are going beyond grants, philanthropy, and traditional financing to explore other ways to support capital projects, including community investment models like community bonds. 

For boards, the biggest barrier is often simply awareness. It’s natural to rely on the funding models you know best. But as projects grow more complex and timelines stretch longer, it’s worth looking beyond the “traditional” paths. Because communities still need these projects, and waiting indefinitely for the perfect funding moment isn’t an option.

A moment for boards to think differently

This is an opportunity for nonprofit boards to shift from “Where will the funding come from?” to “How do we structure funding so projects can keep moving forward?”

That means paying closer attention to timing, building funding strategies that don’t rely on a single source, and becoming more familiar with the full range of available financing tools (including community bonds!). 

While funding environments change, the need for affordable housing, community spaces, health infrastructure, and cultural hubs does not. Boards that understand both the numbers and the capital strategy can act confidently, even when the funding landscape inevitably changes again. 

3 questions every nonprofit should ask before launching a community bond 🧐

Par Education

⏲️ 4 min read

Community bonds let supporters invest directly in the projects they care about – affordable housing, arts and cultural spaces, community hubs, renewable energy, and more. 

For nonprofits, charities, and co-operatives, they can unlock serious capital and deepen community relationships at the same time. 

That’s powerful.

But community bonds aren’t a shortcut. They’re a financing strategy. And like any strategy, they work best when you’re ready for them. 

Before you jump in because you’re excited and community bonds are the best thing ever (yes, this is a fact we made up), pause, and ask yourself these three questions:  

1. Do we have the capacity to run this well?

A community bond campaign needs dedicated operational capacity. It can’t be added onto someone’s role as an afterthought. You need team members with skills in project management, finance, and communications. The team doesn’t have to be all staff. Board members, volunteers, advisors, and dedicated community members can all play a role.

With the right team in place, you’ll actually enjoy the process, instead of running around scrambling. Many nonprofits are already stretched thin. Your financing strategy should strengthen your organization, not exhaust it. 

2. Do we have a clear plan to repay investors?  

Community bonds are debt. 

That means investors want their money back – just like a bank would. What you’ll need to show investors is a credible plan: 

  • What revenue streams will support repayments?
  • Are we being realistic (maybe even conservative) in our assumptions? 
  • Are there flexible or creative ways to structure repayment that work better for our organization?

A strong repayment plan satisfies investors, reassures your board, strengthens your financial governance, and signals that your organization understands the responsibility that comes with borrowing. 

At Tapestry, we work closely with you to design these repayment plans, but the thinking has to start with you. 

3. Is the timing right – do we need to raise capital in the next 8-12 months?

Timing is key. 

Start too early, and you’re carrying debt before you really need it.
Start too late, and your campaign may not finish before you need the funds. 

Aligning your campaign timeline with your actual capital needs is critical. 

Community bonds are a powerful tool, but they take time to design, launch, and close. When timing is right, campaigns feel deliberate, confident, and manageable. When timing is off, even good projects may struggle. 

The bottom line: clarity.

Clarity about your team.
Clarity about repayment.
Clarity about timing.

Community bonds can absolutely transform how your organization finances projects and engages supporters. 

They can unlock new sources of capital, strengthen independence, deepen community engagement, and keep wealth circulating locally. But they work best when the groundwork is solid. 

So ask yourself these three questions. 

And when you’re ready, we can put the pedal to the metal and help you make it all happen – because the foundation will already be in place. 

Want to learn more about raising capital with community bonds? Our Community Capital Readiness Program helps nonprofits, charities, and co-operatives test if community bonds are the right fit for their project. 

Learn more and apply here

Scaling community bonds: unlocking potential for large-scale projects

Par Education

When large organizations first hear about community bonds, their first thought can be: “This is great for grassroots groups, but we’re looking at $100 million projects. Are community bonds for us?

It’s a fair question. Community bonds gained traction with campaigns in the sub-$5M range, often supporting newer or grassroots organizations. And we love supporting these groups!

But community bonds are scalable, flexible, and increasingly powering large, complex projects. They can form a core part of a strategic financing plan for bigger, long-established organizations, unlocking capital while engaging investors and the broader community. 

The power of scalability

Community bonds scale because they are repeatable, transparent, and confidence-building. Each successful campaign demonstrates investor trust in both the organization and model, paving the way for even larger campaigns. 

Our partners are already proving this, doubling or tripling their campaign sizes within a few years:

  • SolarShare’s first raise was $200,000, and they have consistently grown their campaigns, raising $14.3M in just nine months last year.
  • Ottawa Community Land Trust raised $3M in 2024 and is launching a $10M raise this month (under the umbrella of a $25M campaign with Centretown Citizens Ottawa Corporation). 
  • And upcoming campaigns with other issuers are aiming even higher, showing that the market for community bonds is real, growing, and increasingly confident. 

The lesson is clear: with the right guidance, community and market confidence, community bonds have no ceiling.

Investor appetite is growing

One of the most compelling aspects of community bonds is the diverse investor base they attract. Both retail and institutional investors are increasingly eager to participate. According to the 2025 RIA Investor Opinion Survey, 67% of Canadians say they’re interested in responsible investing. Over 90% of community bondholders would be interested in purchasing community bonds again. And at the same time, Canadians are showing a growing preference to direct their resources toward local impact. A 2025 Interac survey found that 79% of Canadians agree that supporting local businesses feels more important than it did last year

While some of this surge may reflect the broader “Buy Canadian” movement, it also signals a strong appetite among Canadians to invest consciously, supporting local and mission-driven initiatives. 

This growing interest extends beyond individual investors. Institutions, foundations, and impact funds are increasingly exploring ways to participate. The launch of Weave Community Capital Fund, a $30M pooled fund investing in issuers of community bonds, signals growing institutional confidence in this model.

With both retail and institutional investment rising, community bonds are uniquely positioned to attract the investors needed to support ambitious projects. Every successful campaign builds trust, momentum, and credibility – demonstrating a real, growing market ready to engage with large-scale, impactful initiatives.

Integrating community bonds into large-scale financing

Community bonds transform the way organizations finance projects. They offer standalone impact and the flexibility to complement other sources when needed. For large-scale projects, community bonds can:

  • Demonstrate public support and credibility, strengthening confidence among other funders, stakeholders, and municipal partners
  • Engage a diverse investor base, retail and institutional, who care about mission-driven impact
  • Rally momentum and community buy-in, unlocking additional capital and helping de-risk large-scale initiatives 
  • Keep a portion of your financing local, returning interest to the community members who support your work rather than only to commercial lenders

By leveraging community bonds strategically, large organizations can finance ambitious projects while generating lasting social impact and community engagement at scale.

A tool for ambitious organizations

Community bonds are a proven, scalable financing tool for ambitious organizations tackling multi-million dollar projects.

For leaders ready to think big, community bonds offer more than just capital. They scale impact, mobilize a diverse investor base, strengthen community and stakeholder trust, and unlock opportunities for ambitious, multi-million-dollar initiatives. 

Large-scale impact requires a lot of capital, but it also requires connection. And community bonds bring both.

When systems fall short, communities can still lead

Par Affordable Housing, Client Stories, Education

Across Canada, communities are facing the dual crisis of rising housing costs and the disappearance of accessible, inclusive spaces. And while headlines may differ from province to province, the underlying challenges – displacement, disinvestment, and inaction – are all too familiar.

Take Québec for example, a province where the housing crisis is made especially visible each year through a long-standing tradition.

Every year on July 1st, a uniquely Québécois ritual unfolds: Le Jour des déménagements, or Moving Day. Originally designed to avoid uprooting school-aged children mid-year, it has become a striking symbol of housing precarity. On this day, tens of thousands of leases expire across the province – sending renters scrambling to move, often with few affordable options. 

In 2024, that precarity reached new heights.

The provincial rental board recommended a rent increase of 5.9%, the highest in decades. Actual rent hikes, especially in units with turnover, are even higher. Evictions across Québec have increased six-fold since 2020 – and that’s only counting reported evictions. In response, housing advocates recently launched a province-wide “week of action”, including the occupation of a vacant, city-owned building that had been promised for social housing – but still sits empty. 

Public programs for social housing have been defunded, and few new options have replaced them. Communities are left wondering: What tools do we actually have? That’s where Brique par Brique comes in. 

A community that isn’t waiting

Rather than waiting on delayed public programs, Brique par Brique, a community organization in Parc-Extension, is mobilizing the power of collective investment. Their $5 million community bond campaign is raising capital to support two critical projects: 

  • A permanently affordable, non-speculative housing development
  • A Centre for Creative & Collective Action that offers space for programming, culture, and community organizing to support organizations working to combat social inequities 

This campaign isn’t just about raising capital. It’s about building power. By inviting residents to co-invest in their own community, Brique par Brique is creating a model of co-ownership, connection, and shared responsibility. 

This isn’t new in Québec

What makes this campaign especially powerful is that it’s grounded in Québec’s long-standing tradition of collective organizing in response to austerity and government retreat. From the rise of co-operatives and caisses populaires (credit unions) to the growth of solidarity unions, Québec communities have long created tools to fill the gaps left by underfunded public systems and market failures. These were tools that gave people control when institutions didn’t.

In fact, while the term “community bond” gained prominence later in Ontario, Québec was home to one of the earliest examples of this kind of financing. In the early 2000s, residents of Sorel-Tracy mobilized local capital to fund a new recreation centre. That campaign helped lay the groundwork for community-led finance models.

Brique par Brique is continuing that legacy. Their campaign doesn’t just use a financial tool; it reclaims one as a vehicle for community power, mutual aid, and long-term stewardship.

Why it matters – even beyond Québec

You don’t have to live in Québec or work in housing to learn from this. 

Brique par Brique’s campaign illustrates a powerful truth: when systems fall short, communities can still lead.

Community bonds aren’t the only answer. But they are a promising one, especially when used by organizations with deep relationships, aligned values, and a clear long-term vision. When done right, community bonds can spark agency, organize communities, and help build infrastructure that truly reflects the people it’s meant to serve. 

At a time when non-profits across Canada are struggling with stalled funding, rising costs, and increased demand, Brique par Brique shows what’s possible when we stop waiting and start building – from the ground up. 

Learn more about Brique par Brique’s community bond campaign here

Data’s cool, but have you tried a good story?

Par Education

Let’s be real – most people aren’t curling up with a cup of tea to read your annual report cover to cover. And while numbers matter, they don’t always spark emotion or connection. 

If you’re part of a nonprofit, charity, co-operative, or social purpose organization, you already know: the real magic happens when people feel something about your work. That’s where storytelling comes in. 

We chatted with our colleague, Jennifer Bryan, Director of Campaigns here at Tapestry to ask about best strategies for effective storytelling and how organizations can do it without needing a full-time communications team or documentary budget. 

Here are five of Jennifer’s storytelling tips to build connection and engagement

1. Loop people in early 🗣️

Planning something big (or small)? Tell your people about it early. Ask for their input. Get their ideas. Let them feel part of it.

“Get a lot of folks interested and involved in the beginning, and take their feedback so they feel a part of it.” Jennifer explains.

The earlier folks feel included, the more likely they are to care about what happens next. And honestly? People are more likely to support something they’ve helped shape. Early involvement = deeper engagement.

2. Always come back to your “why” 🎯

Every stage of your project, from planning to launch to long-term impact, is a chance to connect your audience back to your mission. Why are you doing what you’re doing?

“In the early stages, it’s about potential impact,” Jennifer shares. “What does the organization see the impacts being – and how are those realized once the project is actually completed? All the way through, keeping them informed.” 

Remind people what’s at the heart of it all – not just what you’re doing, but why you’re doing it.

3. Make it human 👥

Reports are great, but a real story? That’s what people remember. 

If your work has helped someone access housing, food, or belonging – and they’re open to sharing their experience – spotlight that

“It’s the stories,” Jennifer says. “That’s what really reaches those people who are like, ‘I don’t want to see numbers on a page. Tell me about the people who live here and what this has done for them’.” 

Bonus tip: Include quotes or first-person voices whenever possible. Let your community hear directly from the people closest to the impact. 

4. Choose one channel and stick to it 📬

You don’t need to be everywhere. Choose one platform that feels doable for your team and stick to it – whether that’s a monthly newsletter, blog, or Instagram stories. It’s better to commit to one channel and update it regularly than to spread your efforts thin across too many. 

Set an achievable target for your team, communicate it to your audience, and then follow through. Consistency > complexity.

5. Be real, not perfect ✨

Every initiative will have its challenges. That means not every update will be a celebration – and that’s okay. When you hit a rough patch, the most important thing you can do is to keep the dialogue going. 

While positive stories of impact are powerful, don’t be afraid to talk about the tough stuff, too. Taking time when it’s needed to share challenges and setbacks transparently will keep your community engaged, maintain trust, and perhaps even rally support when it’s needed most. 

Remember: trust is built in the “in-between” moments, not just the headlines.

TL;DR? 💡

Numbers matter – but stories give them meaning.

Storytelling isn’t about being a pro. It’s about showing the real impact behind the numbers and making it human. By looping people in early, staying focused on your mission, and keeping it real, you’ll build trust, deepen engagement, and make your work resonate with your community. 


Want more content like this? Subscribe to our newsletter for practical tips and behind-the-scenes content. We promise we don’t spam! 😀 

X